Portfolio perspective
Capital allocation is
only half the picture.
Why a balanced-looking portfolio can still depend on a narrow set of return drivers.
Diversification beyond stocks and bonds
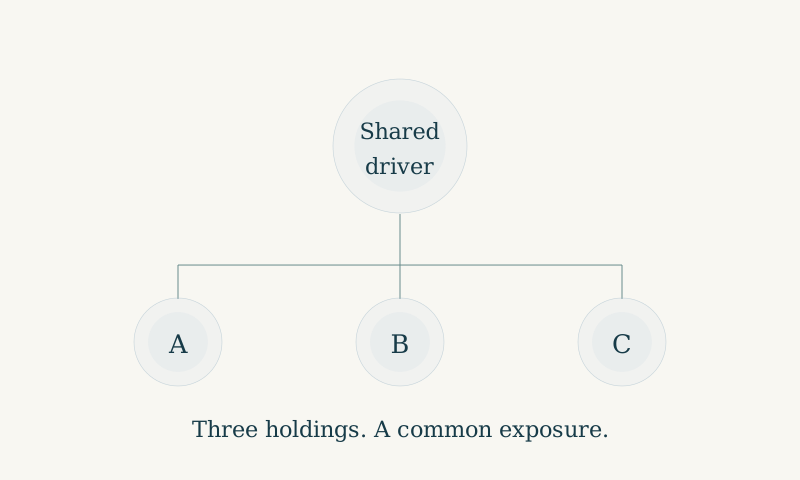
Different holdings.
Different drivers.
True diversification isn’t simply owning more securities. It comes from combining fundamentally different sources of return whose risks respond differently across economic environments.
The model below isolates the relationship between correlation and volatility. It is a mathematical illustration, not a backtest, recommendation or forecast.
A mathematical illustration
Why correlation
matters.
What matters is how the returns of different holdings move together.
Annual portfolio standard deviation

- 60% correlation
- 40% correlation
- 20% correlation
- 10% correlation
- 0% correlation
Illustrative mathematics only. Every stream has equal weight and an equal 10% standalone standard deviation, and each curve assumes a different pairwise correlation. Real portfolios do not have zero correlation among holdings, and correlations can rise in stressed markets, so the benefit shown at low correlations may not be available. These are not Gulfstream returns or forecasts, they do not describe any client portfolio, and they are not a protection against loss.
The principle behind the approach
Ray Dalio’s case for uncorrelated returns.
Dalio describes 15 good, uncorrelated return streams as eliminating about 80% of risk and improving return-to-risk approximately fivefold in his public explanation of the “Holy Grail” of investing.
This is an attributed explanation of the diversification principle, not a Gulfstream performance claim. Dalio’s figures assume uncorrelated return streams. The chart above shows how quickly the effect shrinks as assumed correlation rises, and real investments may not satisfy those assumptions.
Read Dalio’s own explanation (opens in a new tab)Watch the principle explained
Ray Dalio Breaks Down His “Holy Grail”
Video by Investopedia · April 27, 2019
Diversification & correlation
Load the YouTube player to watch here.The player stays off until you choose to load it.
Selected for educational context. This selection does not imply affiliation with or endorsement of Gulfstream by Ray Dalio or Investopedia. The illustration above uses its own stated assumptions.
Model, assumptions and sources
The formula is σₚ = σ × √[ρ + (1 − ρ) / n]. Standard deviation is one measure of risk; it does not describe every form of investment risk. Fees, taxes, leverage, liquidity and tail losses are not modeled. Correlations can change, including during stressed markets.
MIT portfolio theory reference · Dalio’s June 2026 discussion · Download model inputs and calculated values
Apply the principle
with discipline.
Real portfolios involve changing correlations, uncertain expected returns, costs and practical constraints. Diversification does not ensure a profit or protect against loss.
Explore the All Weather approachConventional allocation
The Traditional
60/40 Portfolio
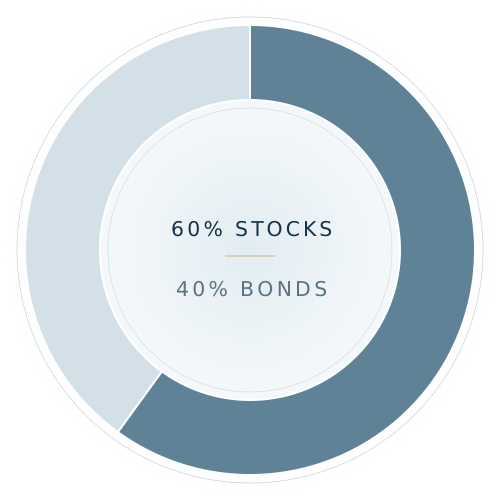
2 core asset classes
A broader framework
Gulfstream
All Weather
20 illustrated return streams