F4 is Gulfstream Capital’s public-filings-driven trading strategy for separately managed accounts using Interactive Brokers (IBKR). The research combines SEC disclosures, data analysis and human judgment to investigate investment opportunities and assess how they may fit within a portfolio.
The process begins with observable transactions and ownership changes. It continues through company research, event analysis and the practical decisions involved in taking, sizing and managing risk.
Source: SEC EDGAR public filings. Filed is the SEC acceptance time in Eastern Time; the trade itself may be a day or more earlier. Only open-market purchases (code P) and sales (code S) in common stock are shown. Grants, option exercises, tax withholding and gifts are omitted. Several trades in one filing are combined; price is the share-weighted average and value is shares × price as reported. Amendments may change these figures. Current price is delayed and includes pre- and after-market trades; change is measured from the trade’s average price, not a return, and is left blank when the two prices are not comparable (for example a different currency or share class). Our analysis links appear only where Gulfstream published an article on that exact filing. A chart for each open-market purchase shows the daily close, the 50-day average, and the reported average price, with the filing kept in view.
This section reproduces facts from public SEC filings for informational purposes. It is not individualized investment advice or a recommendation to buy or sell any security, and the appearance of a filing does not indicate any view of the insider or the company. Insiders trade for many reasons, including taxes, diversification and pre-arranged plans. Gulfstream Capital and its clients may hold positions in securities of companies shown. Not investment advice. Not a recommendation to buy or sell any security.
01 / The research foundation
Why ownership activity matters
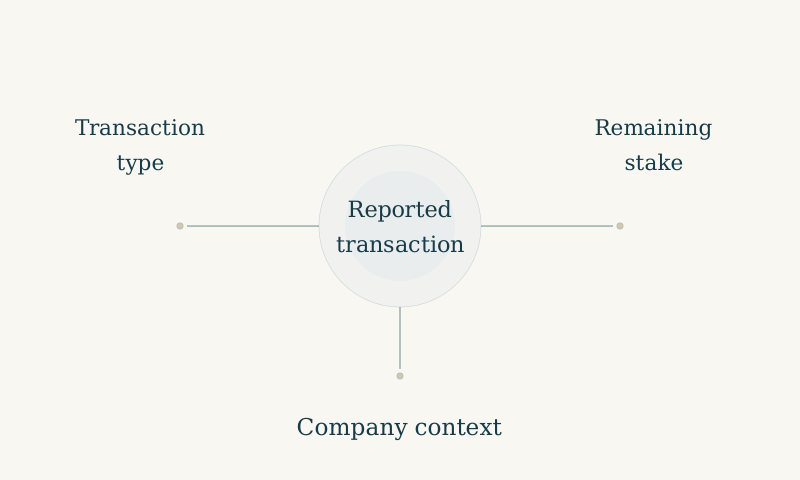
The reported transaction is the starting point; the surrounding context matters.
Corporate executives, directors, major shareholders and institutional managers make decisions that become visible through public disclosures. Those decisions can help focus research on a business, a change in ownership or an event that deserves a closer look.
The useful questions go beyond whether someone bought or sold. How meaningful was the transaction relative to the person’s existing stake? Was it an open-market purchase, an award, an option exercise or another type of transfer? What changed at the company? What expectations might already be reflected in the share price?
Insiders can be wrong. Their reasons for buying or selling may differ from another investor’s objectives, circumstances or time horizon. Publicly reported activity provides evidence to examine, rather than certainty about what happens next.
02 / Public records
Three views of ownership
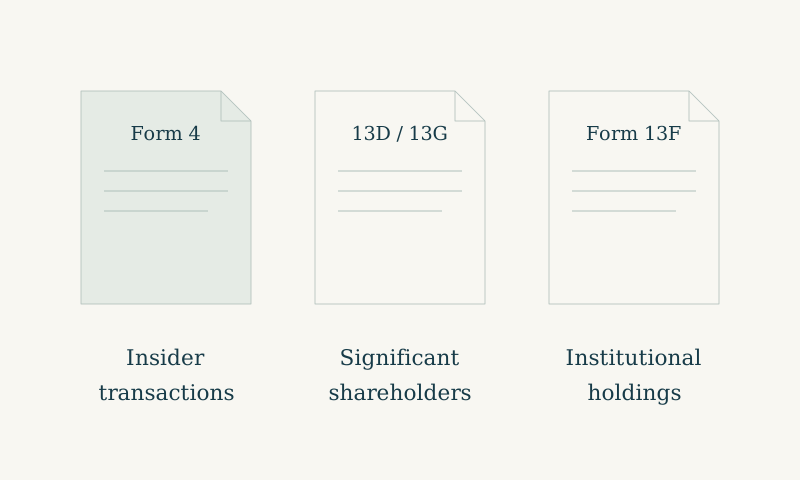
Three public-record lenses on ownership. Conceptual documents, not actual filings.
Form 4
Reported insider transactions
Form 4 discloses changes in ownership by reporting insiders. Transaction codes, footnotes, direct and indirect ownership, and changes in the remaining stake help distinguish purchases and sales from compensation-related or other transactions. Most Form 4 reports are due within two business days of the transaction. The filing records an earlier event.
These disclosures identify certain large beneficial owners. Schedule 13D can also provide context about the purpose of an investment and potential plans involving the company. The applicable filing requirements differ, and amendments matter. A large stake alone does not establish the holder’s intentions or predict an outcome.
Quarterly holdings reports provide another view of ownership. They are generally due within 45 days after quarter-end and cover specified securities. Short positions and other parts of a manager’s portfolio are absent, so a disclosed holding can be stale and does not reveal the manager’s full exposure or hedging.
The filing records an earlier event. Amendments can change the evidence. No specific dates or durations are shown.
01
Screen the public record
Organize reported transactions and ownership changes to identify situations for closer review. The transaction’s type, size, timing and relationship to prior activity help set the research priorities.
02
Read the details
Review the underlying filings, explanatory notes and amendments. A headline number can conceal a very different transaction, and data tools can introduce classification errors or miss relevant context.
03
Build the company and event context
Consider the business, financial condition, valuation and relevant developments. Earnings, financing needs, capital allocation, management changes and corporate events can affect the investment case. A compelling ownership signal still needs a credible company-level explanation.
04
Evaluate portfolio fit and risk
Consider position size, liquidity, concentration, market conditions and how the idea interacts with other exposures. Entry price and implementation matter. Portfolio decisions also require a view of what could invalidate the thesis and when to reassess it.
05
Revisit the evidence
Subsequent filings, company news and price changes can strengthen or weaken an investment case. Research is an ongoing process, and the decision to hold, reduce or exit a position requires judgment as the facts change.
04 / Implementation
Separately managed accounts
F4 is implemented through separately managed accounts using IBKR. Each account’s implementation may differ because of its size, timing, restrictions and other circumstances.
An introductory discussion begins with eligibility and fit. Account requirements and service terms are provided privately during qualification and onboarding. An inquiry does not establish an advisory relationship or guarantee acceptance.
05 / Keep the context
Important limitations and risks
Consider liquidity, position size and existing exposures. These are questions, not allocation weights.
Public filings can be incomplete, delayed, amended or misunderstood. They do not reveal every motivation, position or hedge. Other market participants can review the same information, and prices may already reflect it before an investment is made.
Company-specific events may develop differently from expectations. Concentrated positions can magnify losses, and limited liquidity can make trading more costly or prevent an exit at a desired price. Market declines, execution costs and errors in analysis can adversely affect an account. Portfolio controls and ongoing review cannot eliminate these risks. Investing involves the risk of losing capital.
The publication
Follow the research
Follow Gulfstream news, updates and commentary on Substack and explore the subscription options there. Substack and X posts are news, updates and commentary, not Gulfstream research or investment advice.
Please do not send account numbers, identity documents or financial statements through an initial inquiry.
Important information
This material describes a general research approach and is provided for informational purposes. It is not individualized investment advice or a recommendation to buy or sell a particular security. Any advisory relationship is subject to applicable eligibility requirements and a written agreement. The strategy may be unsuitable for some investors. References to SEC filings and Interactive Brokers do not imply their approval or endorsement of Gulfstream Capital or the F4 strategy.